On Wednesday, the Indian rupee continued its downward trend for the fourth day in a row, reaching a new 5-month low against the US dollar and consequently the UAE dirham.
Just over a week after Prime Minister Narendra Modi’s unexpected demonetization announcement, which removed Rs500 and Rs1,000 notes from circulation, the rupee has dropped nearly 3% against the UAE dirham.
As people in India endure long lines at banks to exchange old notes, non-resident Indians, who might possess numerous demonetized notes, are seeking the best way to manage this sudden surplus.
To the relief of expat Indians, Dh1 now converts to Rs18.53, compared to Rs18.02 on the day Modi revealed the surprise move.
Also read: UAE Exchange no longer accepting old Indian notes
The Indian Supreme Court has urged the government to act swiftly to prevent hardship for ordinary citizens. “The discontinuation of higher denomination notes seems more like carpet bombing than a surgical strike,” the bench noted.
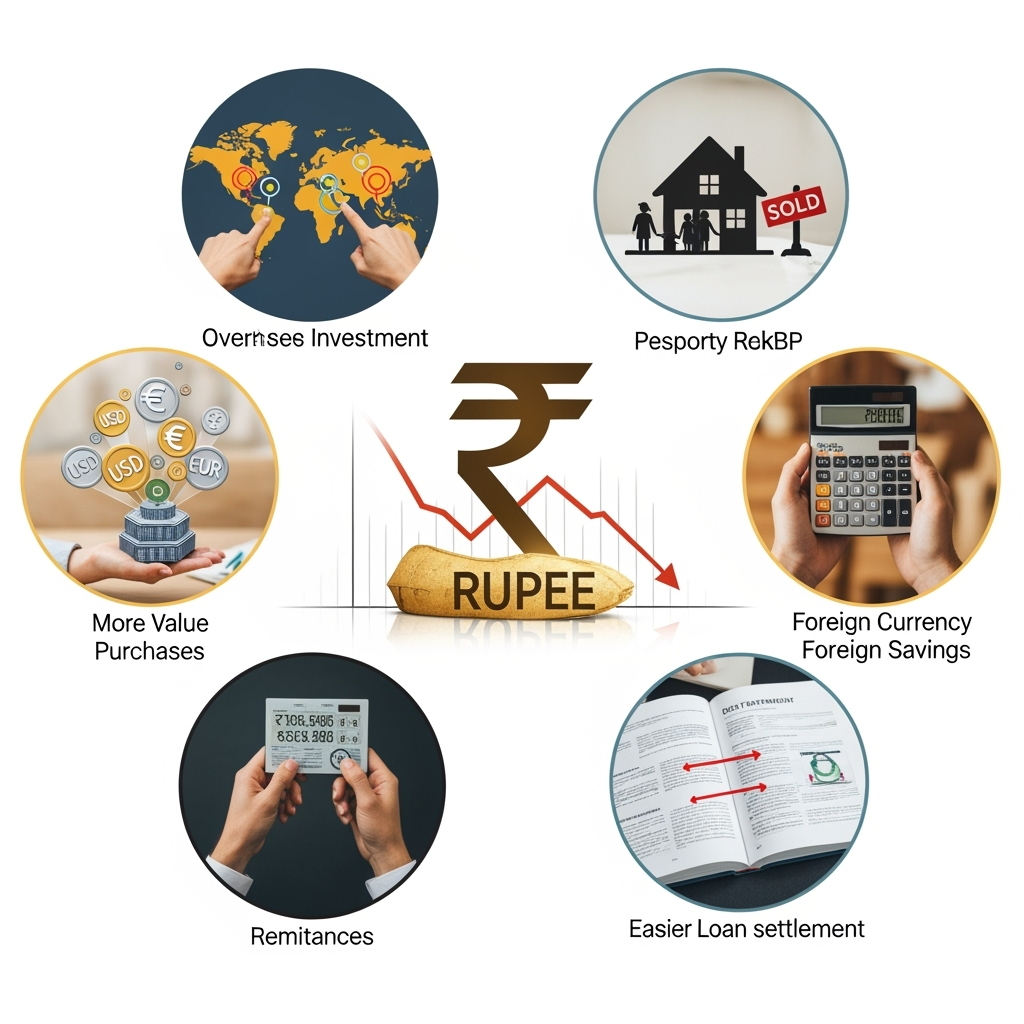
Despite this, the rupee’s falling international value might present a golden chance for expat Indians to clear debts or explore new investments.
Here are 5 ways expat Indians can utilize their newfound wealth:
#1. Purchase ‘distress’ properties in India
With Rs500 and Rs1,000 notes losing value overnight, property deals in India have stalled. Cash payments have dried up, leaving real estate to adjust post-‘carpet bombing’. Those with substantial dirham savings should consider investing in distressed properties with a long-term perspective.
#2. Pay off loans
If you have an outstanding mortgage or loan in India, this is an opportune moment to reduce or settle it, given the favorable dirham/rupee exchange rate.
#3. Invest in stocks
The Indian stock market is as shaken as the rupee, with the Sensex falling by nearly 1,300 points since the announcement. The move ultimately benefits the Indian economy with minimal impact on bluechip companies’ long-term prospects. Current attractive prices offer a good opportunity for long-term investors.
#4. Opt for fixed deposits
Rupee-denominated fixed income options in Indian banks are more appealing than those in dirhams or dollars in the UAE. Consider a five-year fixed deposit with a national or large private bank in India.
#5. Remit funds
Regardless of your plans, you’ll need to remit money to India first. With the favorable exchange rate currently available, now might be the perfect time.
Disclaimer: These suggestions are illustrative and not exhaustive. This article is general and should not be considered as investment advice. Conduct your own research and consult an advisor before making any investment decisions. Khaleej Times is not liable for any losses – direct or indirect – resulting from reliance on this information.