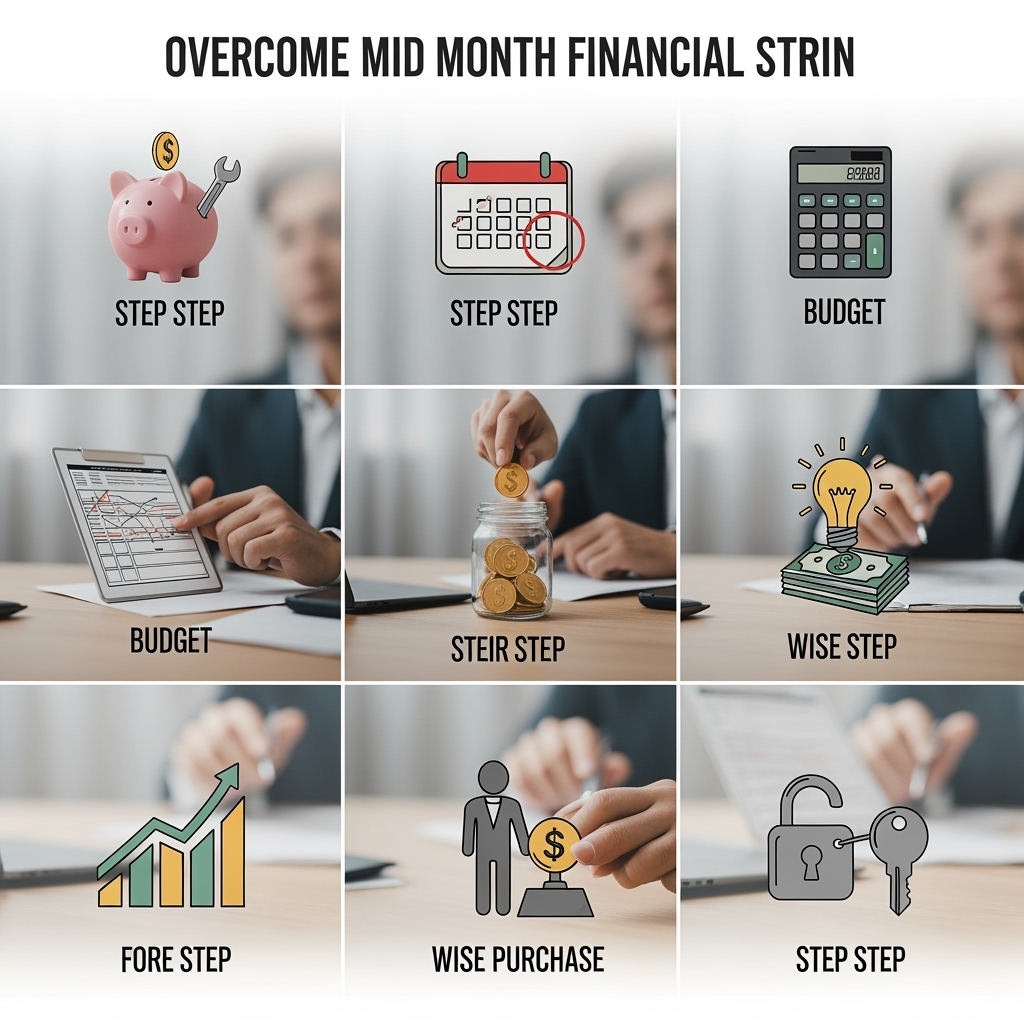
Experts pointed out that running out of salary in the first few days of the month is considered a bad situation, which they termed as the ‘mid-month financial syndrome.’ To combat this ‘mid-month financial syndrome’ and avoid falling into its recurring cycle, financial planning experts advise following 9 steps, as follows: Act as if your salary is 20% less than what you actually earn, and immediately allocate this difference into a side account that you do not touch. For example, if your salary is $1000, plan as if you only have $800 monthly. In this way, you create a financial safety margin for yourself without feeling stressed or deprived.
Stop spending money freely from the beginning of the month and start treating your income as short time periods. Divide your salary into 4 equal parts, and allocate a ‘mini-salary’ for each week. This simple method enhances self-discipline and is similar to receiving a regular daily wage, which helps you avoid early salary depletion and gives you stronger financial control until the end of the month.
Choose a fixed day each week where you completely refrain from spending any money—no shopping, no takeout, no luxuries—just make do with what’s available at home. This simple approach contributes to rationalizing spending, gives you greater control over your daily expenses, extends the life of your budget, and reduces automatic consumption.
Before buying any non-essential product, whether it’s a piece of clothing, an electronic device, or even a new subscription, first place it on a ‘purchase waiting list’ and give yourself at least 7 days or even a month if the value is significant before making a decision. During this period, you’ll discover that many desires were momentary and that your actual need for the product may not have been necessary. This simple method reduces impulsive expenses and gives you smarter budget control without feeling deprived.
Any non-essential purchasing decision should go through a ‘cooling-off’ period of at least one day. This simple delay greatly reduces impulsive decisions and gives you space for rational thinking. A temporary return to cash payment, especially for daily purchases, restores the sense of money’s value and reduces unconscious spending associated with cards. Remove apps that facilitate quick purchases, such as shopping and instant delivery apps, or activate time restriction tools for them, as slowing access helps curb automatic consumption.
Often, automatic subscriptions and unused services are the hidden reason for cash depletion, so make time to review auto-renewing subscriptions. This simple exercise uncovers silent expenses and gives you immediate correction opportunities.
Whenever you want to buy something non-essential, ask yourself: Do I really need that much? For example, instead of buying 10 bottles of water, buy 5, and instead of buying two cups of coffee a day, have one. This simple method does not deprive you of what you love, but it helps you save and think more before repeating purchases, making you buy more slowly.
The study concluded that we need to change our relationship with money. Instead of treating salary as a temporary monthly event, it can be viewed as a continuous tool for building a more conscious and stable lifestyle. In the age of rapid consumption, those who manage their expenses as if every dollar has weight and meaning create sustainable financial security for themselves.