The race for rare earths and crucial minerals is intensifying, and financial advisory leader deVere Group predicts it will be a key investment theme in 2026 as the US and China vie for dominance over materials vital to the modern economy.
Nigel Green, CEO of deVere Group, notes that rare earths have shifted from the fringes to the center of global strategy.
“Securing these resources will influence trade, technology, and investment for years,” Green told BTR.
Moody’s Ratings’ latest report indicates that AI’s rapid global growth is driving up demand for rare earths and other essential minerals. However, geopolitical tensions, especially over rare earths—used in AI and high-tech sectors—are creating vulnerabilities in the tech supply chain.
“Demand could hit 153,000 metric tonnes of rare earth oxides (REOs) by 2040, a 65.5% rise from 2023,” according to the IEA’s policy scenario.
A McKinsey report shows that global demand for magnetic rare earth elements is expected to triple—from 59 kilotonnes in 2022 to 176 kilotonnes by 2035, driven by electric vehicles and wind power projects.
China’s Market Dominance
These minerals, crucial for electric vehicles, smartphones, and advanced weaponry, have long been dominated by China, which controls about 70% of mining and nearly 90% of processing, making manufacturers vulnerable to Chinese policies.
This dominance faces challenges. The Trump administration prioritized rare earths, investing in domestic and allied production.
It has invested in North American miners, proposed a price floor for supply stability, and plans to build a strategic mineral reserve. Permitting is expedited, and environmental rules relaxed for rapid mine construction under the “mine, baby, mine” policy.
“Washington’s move signals a new industrial era. The US aims to regain supply chain control and reduce dependency on Beijing. This is a strategic push for resource security,” says Nigel Green.
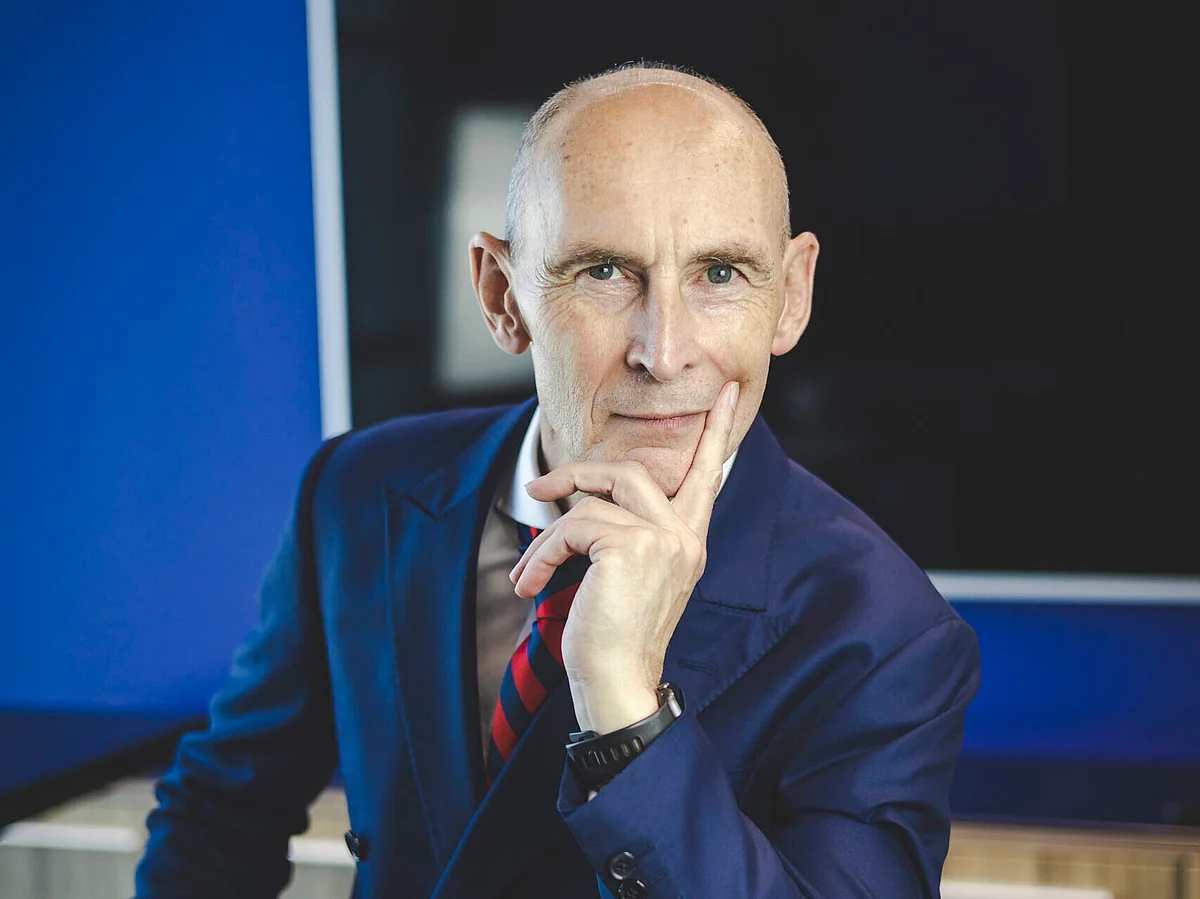
Nigel Green, CEO of deVere Group, stated that rare earths are pivotal in industrial policy, clean energy, and national security.
Meanwhile, China has strengthened its position, imposing new export controls requiring approval for shipping magnets with trace amounts of Chinese-sourced rare earths. It also added five elements—holmium, erbium, thulium, europium, and ytterbium—to its restricted list.
Moody’s Ratings highlighted that China’s dominance in rare earth extraction and processing underpins the global AI hardware ecosystem, especially through crucial components like neodymium magnets and gallium semiconductors, making Western AI, defense, and communications infrastructure vulnerable to Chinese export controls.
“China shows that controlling supply equals market control. The US and allies must build alternative supply chains, sparking unprecedented investment in Australia, North America, and Africa,” says deVere’s CEO.
He emphasized the significant investment implications, stating, “This transformation spans years, not months. Infrastructure and refining capabilities can’t be built overnight. Early investors will benefit from ongoing capital flows into strategic resources.”
DeVere analysts foresee continued sector volatility as governments intervene and policy shifts affect prices.
Nigel Green remarked that these markets will move on policy, not just earnings. “Every export restriction, government stake, and strategic alliance will impact the market. This volatility offers opportunities for disciplined investors.”
He added: “Diversification across the supply chain—from mining to refining to recycling—will be crucial. This is about securing systems that keep economies operational. Savvy investors will be long-term winners.”
He concluded: “Rare earths are at the intersection of industrial policy, clean energy, and national security. The battle for control will shape 2026. The scale of current investments highlights how swiftly the world is adapting to a new economic reality. It’s a significant shift in value creation.”