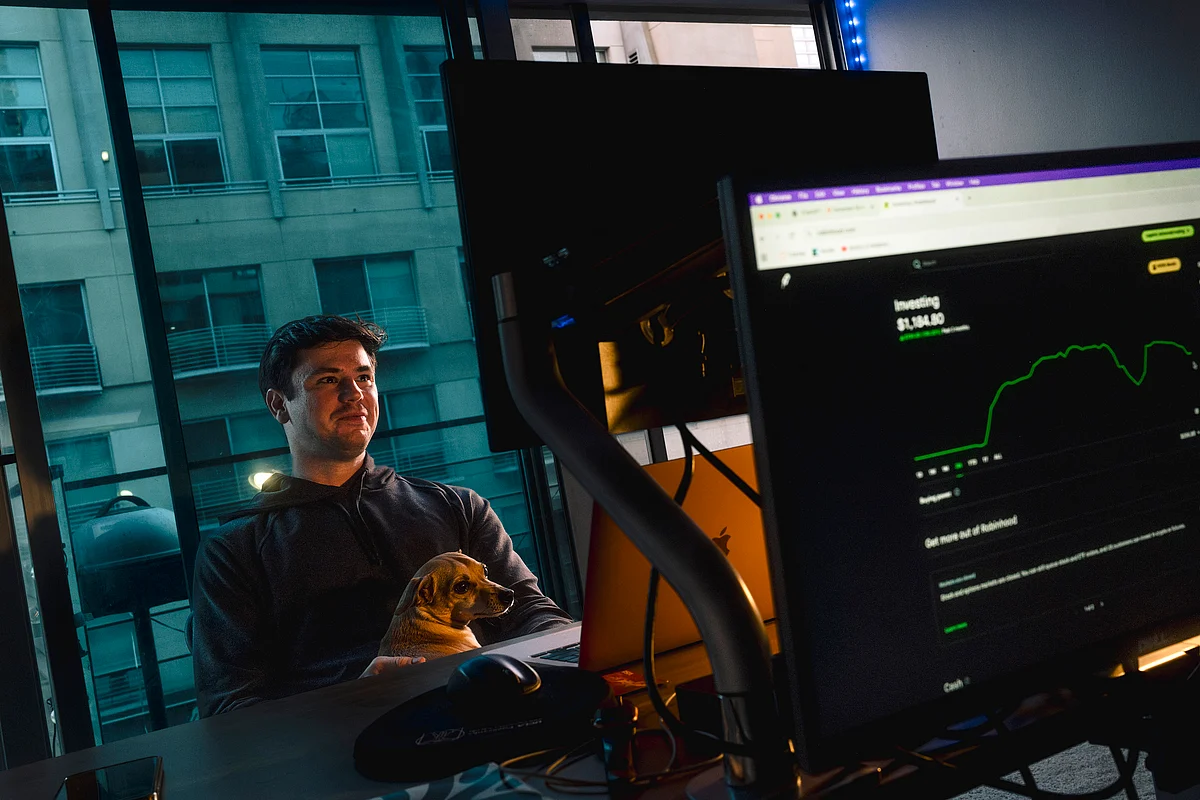
Alexander Stuart, 32, has been using ChatGPT to learn stock trading in Los Angeles as of August 31, 2025. The chatbot has guided him on essential trading tactics, such as risk management and timing trades. — Mark Abramson/The New York Times
When Myra Donohue’s father, a financial planner, offered to assist with her finances, she politely turned him down.
With her accounting background, she felt prepared to handle her $5,000 credit card debt, alongside car payments and other bills. However, once Donohue, 28, reviewed her finances, she found the task daunting, especially with two young sons and her partner recently laid off from his job as an electrician.
In July, she discovered a Facebook post detailing a seven-step approach to managing finances: Step 1 was straightforward: List your income and fixed expenses and create a zero-based budget, where every dollar is assigned a job. Recalling ChatGPT’s efficiency in other tasks, she input her details into the AI chatbot to get a personalized financial plan.
Donohue wasn’t surprised by the chatbot’s advice but appreciated how quickly it produced a customized budget.
AI chatbots have become versatile, serving as therapists, career coaches, romantic partners, or friends. With over half of Americans managing finances independently, many turn to chatbots like OpenAI’s ChatGPT and Google’s Gemini for debt management, saving tips, or investment strategies.
Two-thirds of generative AI users have sought financial advice from it, with about 80% reporting improved financial situations, according to an Intuit Credit Karma survey of over 1,000 people.
Younger generations are particularly open: Around 82% of Gen Z and millennial users have used it for financial guidance.
Despite potential risks like data leaks, misinformation, or odd advice, the allure is understandable. AI chatbots are accessible, fast, and often free or cheaper than human advisors. They also provide a less intimidating option for those hesitant to discuss money issues with others.
However, caution is advised. The Credit Karma survey revealed that over half of Americans who took AI financial advice made poor financial decisions or mistakes.
Advisers suggest verifying AI advice and links with professionals before acting. Chatbots may not question assumptions or gather context, which can be risky for financial advice, says Tyler Gilley, associate wealth adviser at Halbert Hargrove.
Despite this, Donohue feels more confident managing her bills and finances.
“It was really about me getting back on the horse,” said Donohue, a human resources administrator in Grass Valley, California. “I wanted a professional kind of service, but I also wanted to get it done without spending.”
Daily prompts for paying down debt
Jennifer Allan, 35, didn’t realize her credit card debt was escalating. As a real estate agent in Clayton, Delaware, with a newborn daughter and no paid maternity leave, she depended on credit cards for daily needs like diapers and groceries.
“I woke up one day, and I was like, ‘If I use ChatGPT for everything else, why wouldn’t I just use it to help me pay down this debt?’” Allan said.
Her initial prompt was: “I’m in credit card debt. I have no idea how much credit card debt I’m in. I don’t know what to do.”
Owing $23,000, she embarked on a 30-day challenge to focus on reducing her debt. Each day, she asked ChatGPT for a new task to raise money and completed them. She sold a watermelon with her debt amount tattooed on it for $51, recovered $700 from her state’s unclaimed-property registry, and donated plasma for $80, despite her needle phobia. She also saved nearly $600 by using pantry leftovers for meals.
Allan, who documented the challenge on TikTok, managed to pay off nearly half her credit card debt.
ChatGPT also recommended contacting her credit card companies to lower her balance. While they offered to close the cards, she declined.
Budgeting for milestones
According to Empower, a financial services company, people feel most comfortable asking chatbots about budgeting and tracking expenses. For Kathryn Aguilo, a 30-year-old kindergarten teacher, that’s precisely how she used it.
She first used ChatGPT last year to help her and her fiancé save for their 180-person wedding on Long Island, New York. The chatbot recommended cutting back on dining out, setting a $40 limit when they did, and avoiding opening bar tabs. It also suggested using cash instead of cards.
After the wedding, Aguilo turned to ChatGPT to create an expense tracker and budget to save for a home down payment. They closed on a two-bedroom house in January, and Aguilo consulted ChatGPT again for advice on accelerating their 30-year mortgage payments.
“I’m not, like, asking it to create my future children and what they’re going to look like,” Aguilo said. “I do really just use it intentionally for saving, budgeting and to help us.”
Stock market moves
While many use AI just to break even, some leverage it to get ahead. After a breakup and six years in the same accounting job, Alexander Stuart, 32, sought change.
In late June, Stuart asked ChatGPT to serve as a “free college” to teach him about stock investing and how to “become one of the greatest traders.” With $400 to invest, the chatbot guided him on trading strategies, such as managing risk and timing trades.
He tested the advice by investing in AMD, which the chatbot identified as the best option among 500 companies, based on mergers, analyst notes, trading activity, and more. Following the advice, his investment doubled that day.
Now, Stuart’s Robinhood account, a popular trading app, stands at around $1,600 — a significant return, though he acknowledges the gains could vanish quickly. He’s investing for entertainment and learning, not bill-paying.
When your chatbot fails you
Despite some successes with AI financial fixes, others report being misled.
Take Stuart. A month into investing, he lost nearly $60 on an Nvidia trade after discovering a number ChatGPT cited as new was days old, a caution financial experts issue when relying on AI chatbots. Since then, Stuart manually uploads and verifies data before allowing chatbots to guide his investments. He also compares ChatGPT’s advice with Grok, another chatbot.
Uploading information has risks, too. Allan, who completed the 30-day challenge, uploaded her bank statements for personalized AI advice, but advisors recommend keeping personal details and sensitive information, like a Social Security number, away from the chatbot.
This article originally appeared in The New York Times.